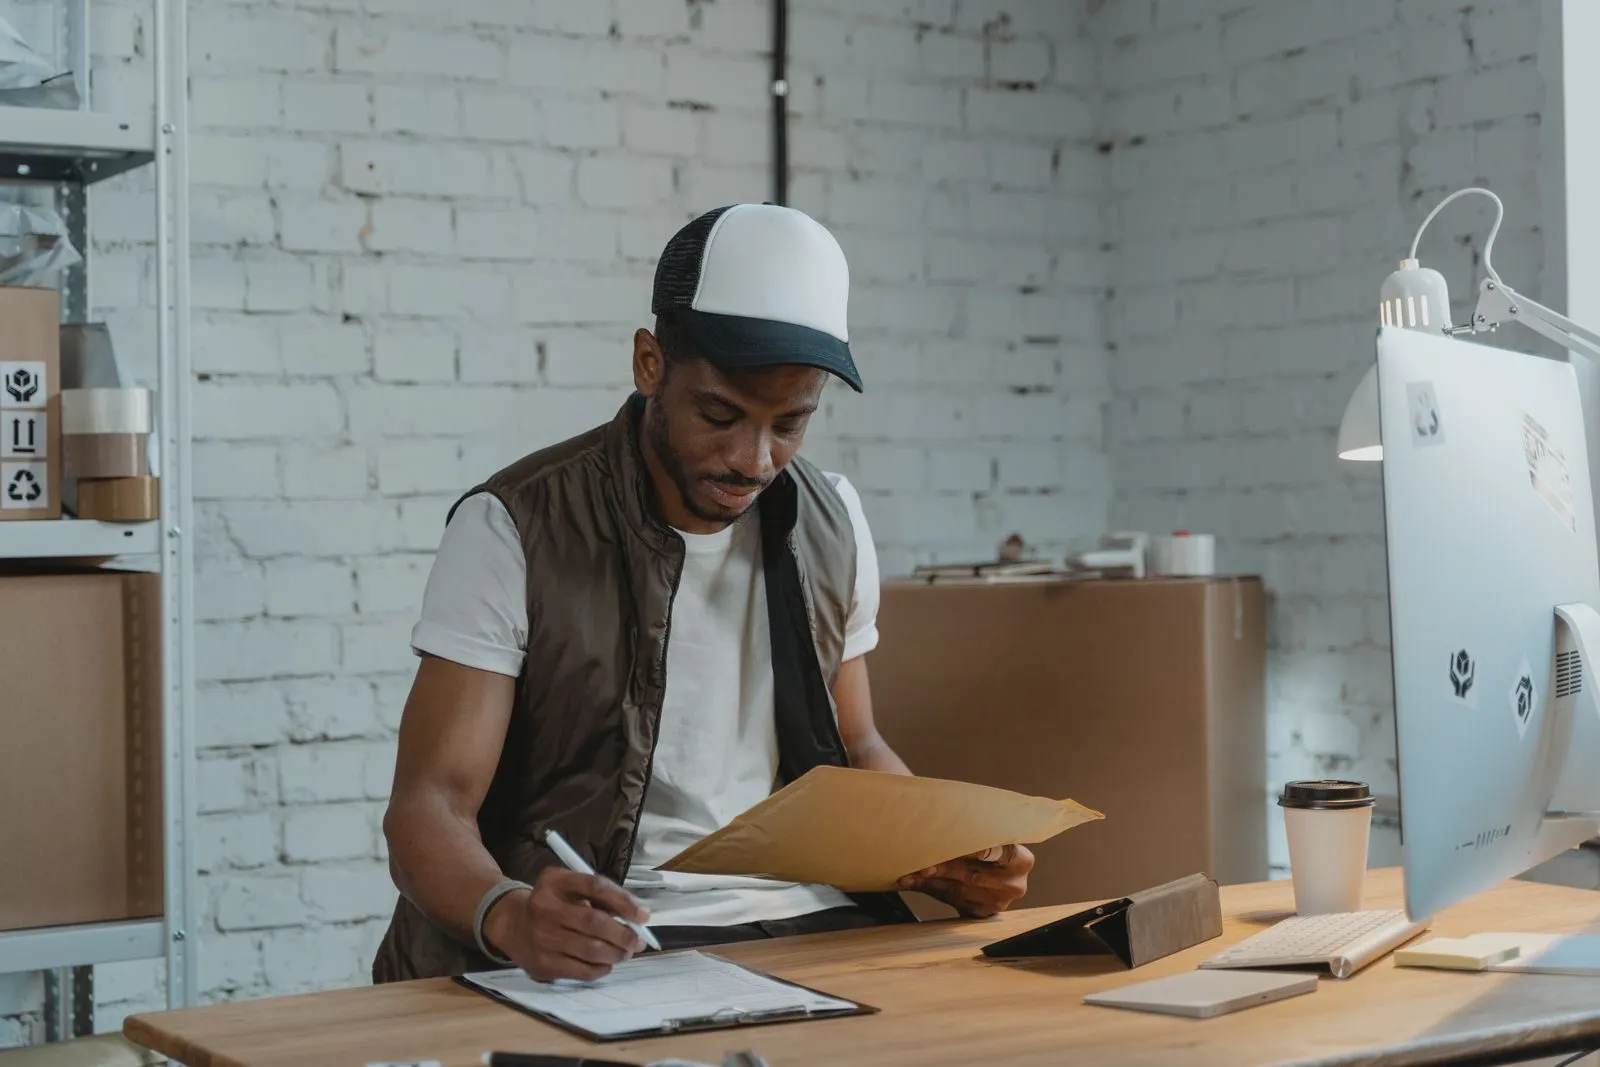
A business owner going through invoices in his warehouse office

Approval based on your customers’ credit · Advances as you invoice · Funding grows with your sales

Turn outstanding invoices into working cash

Turn unpaid invoices into cash now instead of waiting on 30 to 60 day terms.

The short answer

Invoice factoring turns your unpaid customer invoices into cash now: a factoring company advances most of each invoice’s value up front and pays the balance, less its fee, when your customer pays. It suits businesses that sell to other businesses or government on long payment terms, including newer companies, because approval leans mainly on your customers’ credit.

If your customers are reliable but slow to pay (general contractors, national fleets, government), factoring converts that reliability into predictable cash flow. The factoring partner advances the majority of each invoice up front and collects from your customer on the original terms.

Because the credit decision rests mainly on your customers rather than your business, factoring suits newer and fast-growing companies well. Your available funding grows as your receivables grow.

Why CBL

What you can expect

Our partners

Lenders we work with

Banks, credit unions and specialty lenders across Canada. We match your file to the ones that fit it.

How it works

A straightforward process

  1. Step 1

    Share your receivables aging

    Who owes you, how much, and how long it’s been outstanding. That’s the core of the application.

  2. Step 2

    Facility established

    We match you with a factoring partner experienced in your industry and go through the fees with you before you sign.

  3. Step 3

    Invoice and draw

    Submit invoices as you issue them and receive an advance against each one.

A business owner at a desk going through paperwork with a laptop open

Eligibility

What lenders look for

Requirements vary by program. Not sure you qualify? Apply and a person at CBL will review your file.

  • B2B or government invoices for completed work
  • Creditworthy commercial customers
  • Startups considered, since customer credit carries much of the application
FAQ

Questions owners ask

What does invoice factoring cost?

Factoring costs a discount fee on each invoice, and the rate depends on your volume and how quickly your customers pay. A useful comparison is the revenue you would give up by turning down work you cannot float until customers pay. We can model the cost on your actual receivables.

Will my customers know I’m factoring?

Usually yes: in standard (notification) factoring, your customers send their payments to the factoring partner. This is routine in industries like transportation and construction. Where discretion matters, non-notification facilities are available for qualifying businesses.

Working capital loan or line of credit: which is right for me?

It depends on the need: a working capital loan suits a defined, one-time expense, and a line of credit suits costs that come and go. The loan gives you a lump sum that pays down on a fixed schedule. A line stays open to draw, repay and draw again, with interest only on what you use.

Start your application

Ready when you are

Apply in one sitting. Approvals can come the same day. Questions? Call 877-522-2498.

Start your application
A Canadian flag flying over the Rocky Mountains near Banff