CNC and Fabrication Equipment Financing in Canada: Lease and Loan Terms for Machine Shops
How Canadian fabrication shops finance CNC machines, laser cutters and press brakes, with lease vs. loan terms, CCA classes and CSBFP options.
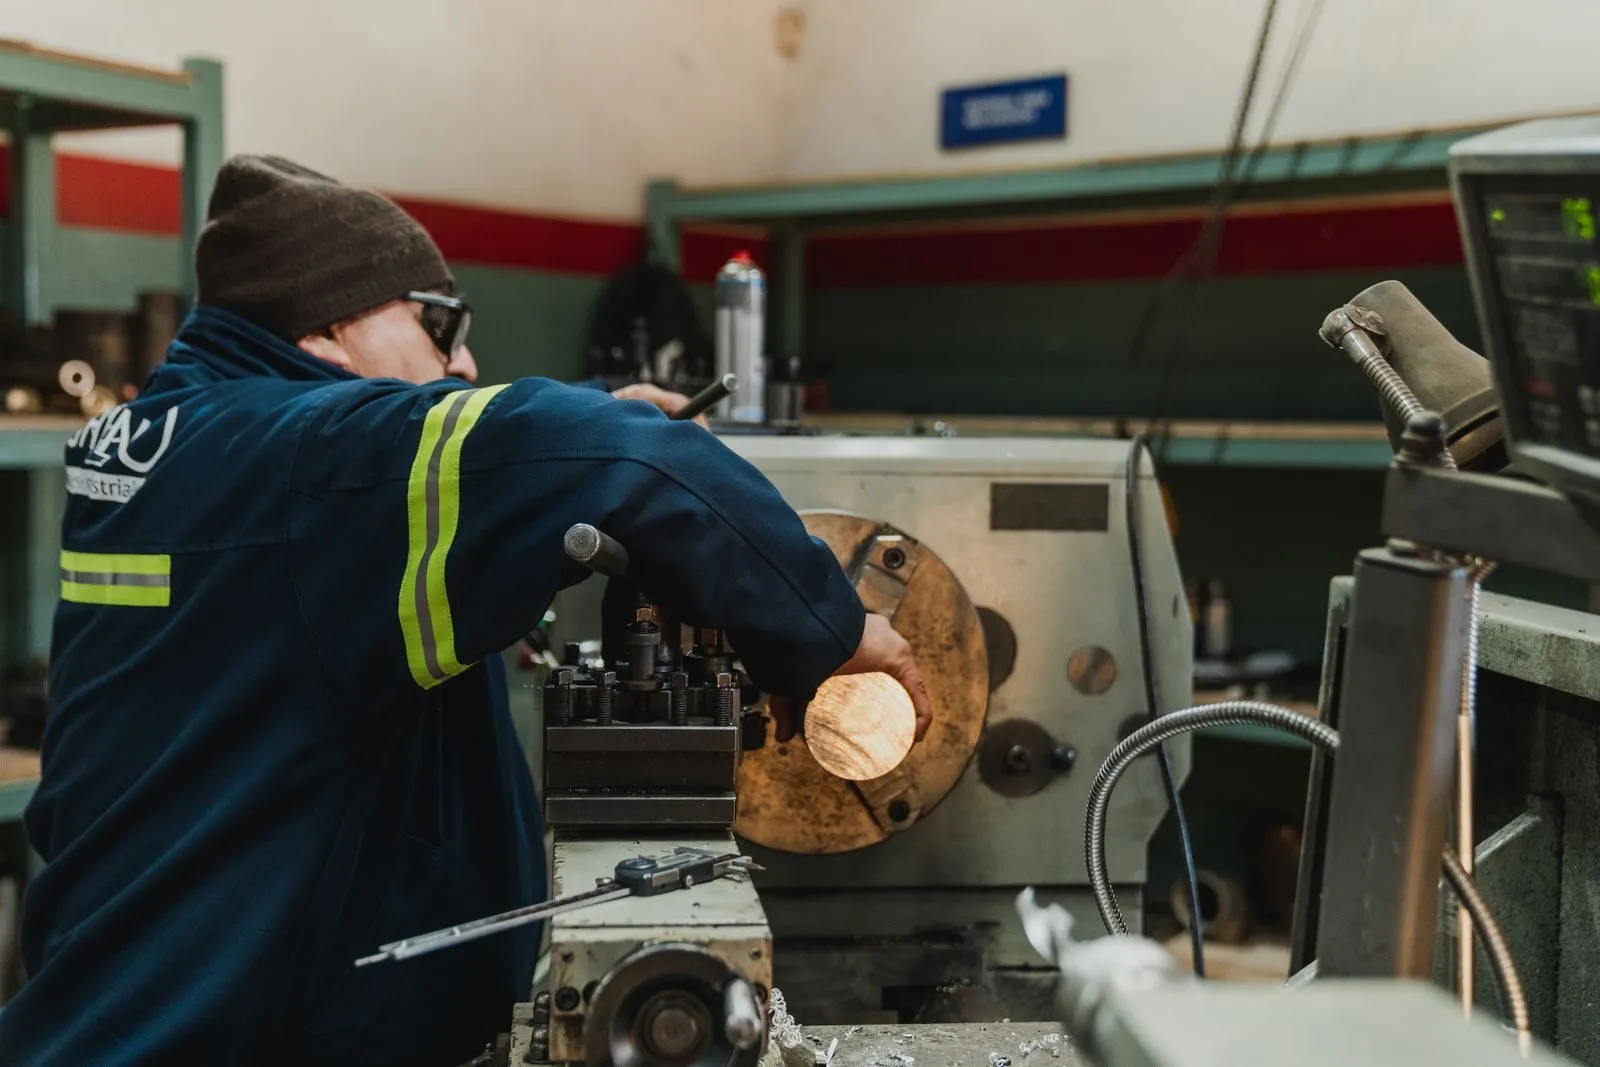
CNC and fabrication equipment financing covers the leasing and loan options Canadian machine shops and metal fabricators use to acquire machining centres, fibre laser cutters, press brakes, plasma tables and related production equipment. A single CNC machine can represent a year or more of a shop’s profit, so most buyers spread the cost across monthly payments matched to the revenue the machine produces. Both new and used equipment qualify, including machines sourced from dealers, auctions or private sales.
Key takeaways
- CNC machining centres, fibre laser cutters, press brakes and plasma cutters all qualify for equipment financing or leasing, including used machines from auctions and private sales.
- Manufacturing equipment acquired in 2026 falls into CCA Class 43 at 30% declining balance, with enhanced first-year deductions available under the Accelerated Investment Incentive for property placed in service before 2028.
- 98% of Canada’s 4,180 machine shops and precision fabrication businesses (NAICS 3327) are small businesses, meaning most buyers are financing against moderate revenue.
- The Canada Small Business Financing Program backs equipment loans up to $500,000 for businesses with annual revenue under $10,000,000, which covers most independent fabrication shops.
| Item | Detail |
|---|---|
| Funding available | Up to $1,000,000 through CBL Financial |
| Terms | 24 to 72 months |
| CCA class (2026 acquisitions) | Class 43 at 30% declining balance |
| CSBFP equipment loan cap | $500,000 per borrower |
| Average machine shop revenue | $877,700 per year (NAICS 3327, as of 2024) |
| Approval speed | Same-day approvals available |
What counts as fabrication equipment for financing
Lenders finance the machines that produce revenue in a fabrication shop. The common categories:
- CNC machining centres and lathes. Vertical and horizontal mills, turning centres and multi-axis machines. These hold their resale value well relative to other industrial assets, which makes them straightforward collateral for a lender.
- Fibre laser cutters. Flat-sheet fibre lasers have largely replaced CO2 lasers in Canadian shops over the past decade. They cut faster, use less power and require less maintenance, though entry prices remain high.
- Press brakes. Hydraulic and electric press brakes for sheet metal bending. CNC-controlled press brakes with servo-electric drives carry higher purchase prices but lower operating costs.
- Plasma and waterjet cutters. CNC plasma tables for thicker steel plate work, and waterjet cutters for materials that cannot take heat. Both are financed routinely.
- Saws, shears, rollers and welding cells. Supporting equipment that rounds out a shop’s capability. Some lenders will bundle several items into a single financing package.
Used equipment is common in this industry. A well-maintained CNC lathe from a closing shop or an auction can have decades of working life left. CBL arranges financing for used machines from any seller, not only dealers.
Lease vs. loan for fabrication equipment
The choice between equipment leasing and an equipment financing loan depends on how long you plan to keep the machine and whether you want it on your balance sheet.
| Equipment lease | Equipment loan | |
|---|---|---|
| Ownership | Lessor owns the machine during the term | You own the machine from day one |
| End of term | Return, upgrade or buy out at a pre-set residual | The machine is yours, fully paid |
| Balance sheet | Lease payments as an expense; IFRS 16 requires on-balance-sheet recognition for most leases | Debt plus the asset on your balance sheet |
| CCA deduction | Lessor claims CCA; you deduct lease payments as a business expense | You claim CCA at 30% (Class 43) |
| Upgrade path | Return at term end and lease newer technology | Sell privately or trade in |
| Cash outlay | Lower monthly payments; possible first-and-last structure | May require a down payment; higher monthly payments but you build equity |
Pro tip: If you are comparing a lease and a loan on the same machine, run both scenarios through the equipment financing calculator and then factor in the CCA tax savings on the loan side. The loan usually looks better on total cost for equipment you plan to keep for its full working life, while the lease wins when you expect to trade up within a few years. For a broader comparison of the two structures, see our guide to lease and loan advantages.
CCA treatment for manufacturing equipment
CNC machines, laser cutters, press brakes and other fabrication equipment used primarily (more than 50% of the time) to manufacture goods for sale qualify for CCA Class 43 at 30% declining balance. This is the standard class for manufacturing and processing equipment acquired in 2026 and beyond.
For context: equipment acquired between 2016 and 2025 fell into Class 53 at 50%, a temporary enhanced class that has now expired for new purchases. The shift from 50% to 30% means the CCA deduction spreads over more years, which affects cash-flow planning on large acquisitions.
The Accelerated Investment Incentive still applies to Class 43 property placed in service before 2028, providing an enhanced first-year deduction by suspending the standard half-year rule. Ask your accountant to calculate the exact first-year write-off for your purchase timing, since the incentive is phasing down through 2027.
Equipment not used primarily for manufacturing (for example, a machine used mainly for in-house repairs rather than production for sale) would fall into Class 8 at 20% instead. The 50% threshold is based on actual use, not the equipment’s capability. For a detailed walkthrough of CCA classes and deduction calculations, see our equipment financing tax benefits guide.
Heads-up: The CNC control computer built into a machining centre is part of the machine’s capital cost for CCA purposes. You do not need to split it into a separate class. CRA’s Income Tax Folio S4-F15-C1 confirms that a computer used as an integral part of a manufacturing process is included in the manufacturing and processing capital cost.
The Canada Small Business Financing Program
The CSBFP is a federal loan guarantee that reduces the lender’s risk on equipment loans to small businesses. For fabrication shops, the relevant details as of October 2026:
- Equipment loans up to $500,000 per borrower (shared with leasehold improvements).
- Open to businesses with gross annual revenue under $10,000,000. The average Canadian machine shop earns $877,700 per year, well within the threshold.
- A 2% registration fee on the loan amount.
- An annual administration fee of 1.25% on the outstanding balance.
- Maximum term of 15 years for equipment.
- Floating interest capped at prime plus 3%, with the Bank of Canada policy rate at 2.25% as of October 2026.
The CSBFP makes sense for newer or smaller shops that may not yet have the credit history for conventional bank terms. The government guarantee gives the lender a backstop, which often translates to lower rates and higher approval odds than an unsecured alternative. The $500,000 cap covers most single-machine purchases, though shops buying a full cell (machining centre plus tooling plus material handling) may need a combination of CSBFP and conventional financing.
What lenders look at for a fabrication file
The equipment and the business both get scrutinized. Here is what moves a fabrication financing application forward.
-
The machine. Brand, model, age, condition and provenance. Established brands with Canadian service networks are easier to underwrite than unknown imports with no local support. Used machines need a verifiable serial number and an honest assessment of remaining life.
-
Revenue and backlog. A shop with steady contract work or purchase orders has a clearer path to approval than one that depends entirely on walk-in jobs. Lenders want to see that the machine will produce revenue from close to day one.
-
Time in business. Established shops have more options. Newer shops can still qualify, but the equipment typically acts as the primary collateral and the owner’s personal credit carries more weight. For more on how lenders assess newer businesses, see our startup equipment financing guide.
-
Personal credit. The owner’s credit score matters, especially for smaller operations where the business and personal finances overlap. A stronger score opens more lenders and better terms.
-
Existing debt load. Lenders check total obligations against revenue. A shop that already carries significant lease or loan payments on other equipment may need to show that the new machine adds enough capacity to cover its own payments.
How CBL Financial can help
CBL Financial arranges equipment financing and equipment leasing for CNC machines, laser cutters, press brakes and other fabrication equipment across Canada, with funding up to $1,000,000 and terms from 24 to 72 months. One application goes to multiple lenders, and approvals can come the same day for straightforward files. If you are ready to look at numbers, apply online or start with the equipment financing calculator.
Frequently asked questions
Can I finance a used CNC machine from an auction or private sale?
Yes. CBL arranges financing for used equipment from dealers, auctions and private sellers. The machine needs a verifiable serial number and reasonable remaining service life. Lenders may ask for a condition report or appraisal on older equipment, and terms may differ from new machine financing, but used CNC machines are financed routinely.
What CCA class does a CNC machine fall under?
Manufacturing equipment used primarily (more than 50% of the time) to produce goods for sale falls into CCA Class 43 at 30% declining balance for property acquired in 2026 and later. Equipment acquired between 2016 and 2025 was eligible for Class 53 at 50%. Confirm the classification with your accountant based on your specific use.
How much can I finance through the CSBFP for shop equipment?
The CSBFP backs equipment loans up to $500,000 per borrower, shared with leasehold improvements. Your business must have gross annual revenue under $10,000,000. The program charges a 2% registration fee and a 1.25% annual administration fee, with interest capped at prime plus 3%.
Is leasing or buying better for a laser cutter?
It depends on your upgrade plans. Laser technology advances quickly, so if you expect to move to a higher-wattage or newer-generation machine within a few years, a lease lets you return the machine and upgrade without the resale step. If you plan to run the machine for its full working life, buying builds equity and lets you claim CCA directly.
Do I need a down payment to finance fabrication equipment?
It depends on the lender, the equipment and your credit profile. Some structures require no money down on strong files, while others require a portion of the purchase price. Used equipment and newer businesses are more likely to need a down payment. CBL presents your file to multiple lenders so you can compare what each one requires.
Can I bundle multiple machines into one financing package?
Yes. Many lenders allow you to combine several pieces of equipment into a single lease or loan, which simplifies payments and can improve overall terms. This is common for shops adding a cell (for example, a machining centre, a tool presetter and a chip conveyor together).
General information, not financial advice.