Aesthetic and Medspa Equipment Financing in Canada: How to Structure a Deal and What Lenders Check
How Canadian medspas finance lasers, IPL and body contouring devices through leasing or loans, plus CCA treatment and CSBFP options.
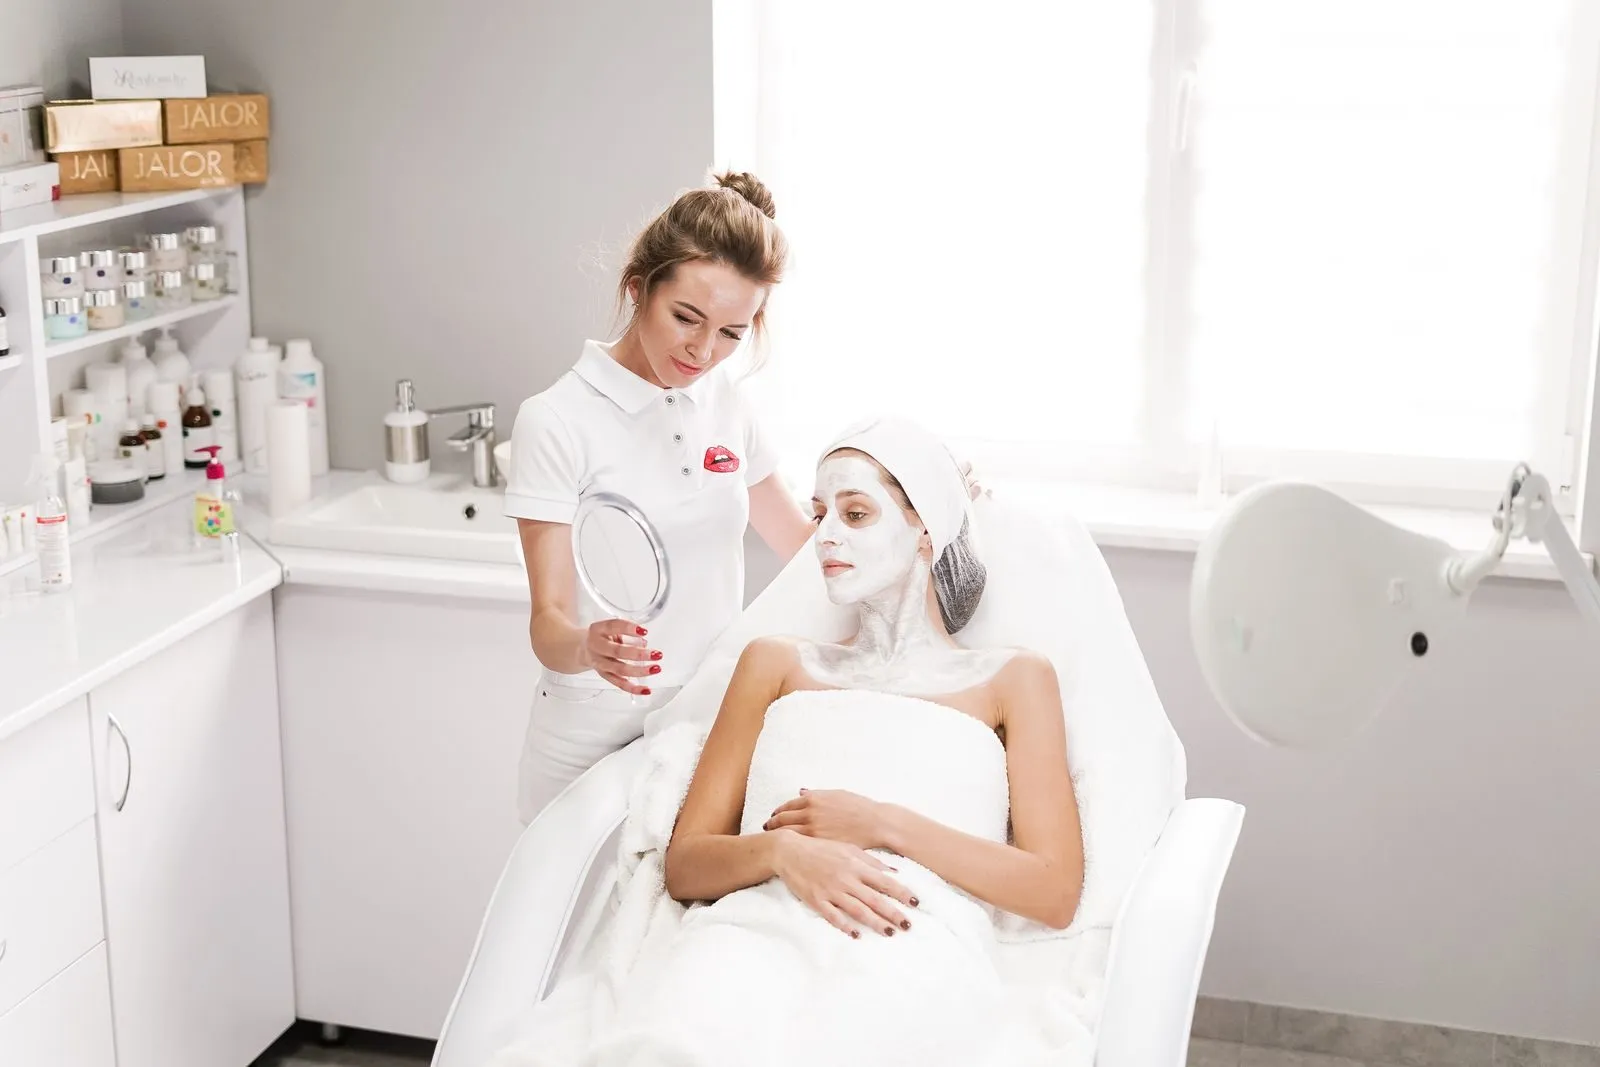
Aesthetic and medspa equipment financing covers the leasing and loan products Canadian clinics use to acquire devices like medical lasers, intense pulsed light (IPL) systems and body contouring machines. These devices are regulated by Health Canada as Class III medical devices, and they carry price tags that can dwarf every other line item in a clinic’s startup or expansion budget. Financing spreads that cost across monthly payments matched to the revenue the device brings in, rather than draining operating cash up front.
Key takeaways
- Medical lasers, IPL and body contouring devices must hold a Health Canada Medical Device Licence before they can be sold or imported into Canada, which means lenders can verify provenance before funding.
- Most aesthetic devices fall under CCA Class 8 at 20% declining balance, with enhanced first-year deductions available for property placed in service before 2028 under the Accelerated Investment Incentive.
- Leasing lets a clinic upgrade to next-generation devices at the end of each term without carrying a depreciating asset, which matters in a field where technology turns over quickly.
- The Canada Small Business Financing Program backs equipment loans up to $500,000 for businesses with annual revenue under $10,000,000, making it a practical path for newer clinics.
| Item | Detail |
|---|---|
| Funding available | Up to $1,000,000 through CBL Financial |
| Terms | 24 to 72 months |
| CCA class | Class 8 at 20% declining balance |
| CSBFP equipment loan cap | $500,000 per borrower |
| Health Canada classification | Lasers and IPL are typically Class III medical devices |
| Approval speed | Same-day approvals available |
What makes aesthetic equipment a distinct financing file
Lenders underwrite aesthetic devices differently from a skid steer or a delivery truck. Three things shape the conversation.
High unit cost relative to the practice’s revenue. A single laser platform or body contouring system can represent a large share of a medspa’s annual revenue. Statistics Canada reports 35,713 businesses in the hair care and esthetic services category (NAICS 81211), with average revenue of $173,300 per business as of 2024. A device that costs six figures against that revenue base means the financing structure has to leave room for the clinic’s other operating costs.
Regulated assets. Health Canada classifies therapeutic lasers and IPL devices as Class III medical devices under the Medical Devices Regulations. They must carry a valid Medical Device Licence before they can be sold or imported into Canada. That regulatory paper trail actually helps the financing process: a licensed device with a verifiable serial number and manufacturer provenance is easier for a lender to underwrite and to recover if needed.
Technology cycles. Aesthetic technology advances quickly. A platform that is current today may be superseded within a few years, which affects residual value. This is one reason leasing is popular in the medspa space: it lets the clinic return or upgrade the device at the end of the term rather than holding a depreciating asset.
Leasing vs. a loan: which structure fits
The choice between equipment leasing and an equipment financing loan comes down to whether you want to own the device or use it.
| Equipment lease | Equipment loan | |
|---|---|---|
| Ownership | Lessor owns the device during the term | You own the device from day one |
| End of term | Return, upgrade or buy out at a pre-set residual | The device is yours, fully paid |
| Balance sheet | Lease payments recorded as an expense; IFRS 16 requires on-balance-sheet recognition for most leases | Debt plus the asset on your balance sheet |
| CCA deduction | Lessor claims CCA; you deduct lease payments as a business expense | You claim CCA on the device at 20% (Class 8) |
| Upgrade path | Return at term end and lease the next generation | Sell the device privately or trade in |
| Cash outlay | Lower monthly payments; possible first-and-last structure | May require a down payment; higher monthly payments but you build equity |
Pro tip: If you plan to keep a device for its full working life, a loan builds equity and lets you claim CCA directly. If you expect to upgrade within a few years (common with body contouring technology that moves quickly), a lease avoids the resale headache. Compare both structures side by side using the equipment financing calculator.
CCA treatment for aesthetic devices
Most aesthetic equipment falls under CCA Class 8, which covers property not specifically included in another class, at a 20% declining-balance rate. Small instruments that cost less than $500 each (applicator tips, for instance) qualify for Class 12 at 100%, meaning full write-off in the year of purchase.
Under the Accelerated Investment Incentive, property placed in service before 2028 gets an enhanced first-year deduction: the half-year rule is suspended, so you apply the full CCA rate to the net addition in the year the device goes into use. For a $150,000 laser in Class 8, that means a first-year deduction of $30,000 instead of $15,000 under the regular half-year rule.
If you lease the device, the lessor claims CCA and you deduct the lease payments as a business expense instead. Either way, the tax treatment should factor into your total cost of ownership comparison. Confirm the details with your accountant.
The Canada Small Business Financing Program
The CSBFP is a federal loan guarantee program that reduces the lender’s risk on loans to small businesses. For clinics acquiring aesthetic equipment, the relevant details as of October 2026:
- Equipment loans up to $500,000 per borrower (shared with leasehold improvements).
- Open to businesses with gross annual revenue under $10,000,000.
- A 2% registration fee on the loan amount, charged upfront.
- An annual administration fee of 1.25% on the outstanding balance.
- Maximum term of 15 years for equipment loans.
- Interest capped at the lender’s prime rate plus a fixed spread, with the Bank of Canada policy rate at 2.25% as of October 2026.
The CSBFP is worth considering for newer medspas that may not yet qualify for conventional bank financing on competitive terms. The government guarantee makes lenders more willing to approve the file, and the program’s rates tend to be lower than what alternative lenders charge.
Heads-up: The $500,000 equipment cap is shared with leasehold improvements. If you are financing a build-out and equipment together, the combined CSBFP borrowing for both categories cannot exceed $500,000.
What lenders look at
Every lender weighs the file differently, but these factors come up consistently when a medspa applies for device financing.
-
The device itself. Is it new or used? Does it carry a valid Health Canada Medical Device Licence with a verifiable serial number? What is the manufacturer’s warranty and service network status? Lenders prefer devices from established manufacturers with Canadian service support.
-
Revenue and time in business. A clinic with two or more years of history and steady revenue has more options. Startups can still qualify, but the device typically acts as the primary collateral and the owner’s personal credit carries more weight.
-
Personal credit. The owner’s credit profile matters, especially for smaller clinics where the business and personal finances are closely linked. A stronger score opens more lenders and better terms.
-
The business case. How many treatments per week does this device need to cover its financing cost? Lenders do not usually ask for a formal business plan, but a clear explanation of the device’s revenue potential helps the file move.
-
Insurance. Aesthetic devices need equipment insurance, and lenders require proof of coverage before funding. Professional liability insurance specific to the treatments the device delivers is also standard practice.
Vendor financing vs. independent financing
Device manufacturers and distributors sometimes offer financing at the point of sale. These programs can be convenient: one transaction, one contact, and sometimes promotional terms on new model launches.
The trade-off is that vendor financing typically covers only that vendor’s equipment, and the terms may not be the strongest available. A promotional rate can come bundled with a higher equipment price or restrictive end-of-term conditions.
An independent application through a broker gives you access to multiple lenders competing on the same file. You can compare the vendor’s offer against others on rate, term and structure before committing. For a broader look at how equipment financing structures work, see our guide to equipment lease options.
How CBL Financial can help
CBL Financial arranges equipment financing and equipment leasing for aesthetic and medspa devices across Canada, with funding up to $1,000,000 and terms from 24 to 72 months. One application goes to multiple lenders, and approvals can come the same day for straightforward files. If you are ready to look at numbers, apply online or start with the equipment financing calculator.
Frequently asked questions
Can I finance used aesthetic equipment?
Yes. Used devices from a dealer, auction or private sale can be financed as long as the equipment has a verifiable serial number and reasonable remaining service life. Lenders may require an appraisal or condition report, and the terms may differ from new equipment financing. CBL arranges financing for used medical devices routinely.
Do I need a medical licence to get equipment financing?
The financing itself does not require you to hold a medical licence. However, Health Canada requires that the devices themselves hold a valid Medical Device Licence, and provincial regulations govern who can operate them. Lenders care about the device’s regulatory status, not your professional designation, but they want to see that the device will be used in a compliant setting.
How does the CSBFP compare to conventional equipment financing?
The CSBFP provides a government guarantee that makes lenders more willing to approve applications from newer or smaller businesses. It caps interest at prime plus a spread and charges a 2% registration fee plus 1.25% annual administration fee. Conventional financing skips those fees but may carry a higher rate for borrowers who do not yet have an established lending relationship. Both paths are worth comparing on total cost.
What CCA class does a medical laser fall under?
Most medical lasers and aesthetic devices fall under CCA Class 8 at 20% declining balance. Small instruments under $500 qualify for Class 12 at 100%. If the device is placed in service before 2028, the Accelerated Investment Incentive provides an enhanced first-year deduction. Confirm the classification with your accountant for your specific situation.
Can a startup medspa get financing for a laser?
Startups can qualify. The device acts as collateral, which reduces the lender’s risk. The owner’s personal credit and any relevant industry experience carry extra weight when the business has limited history. The CSBFP is particularly useful for startups because the government guarantee helps offset the lender’s concern about a short track record.
General information, not financial advice.